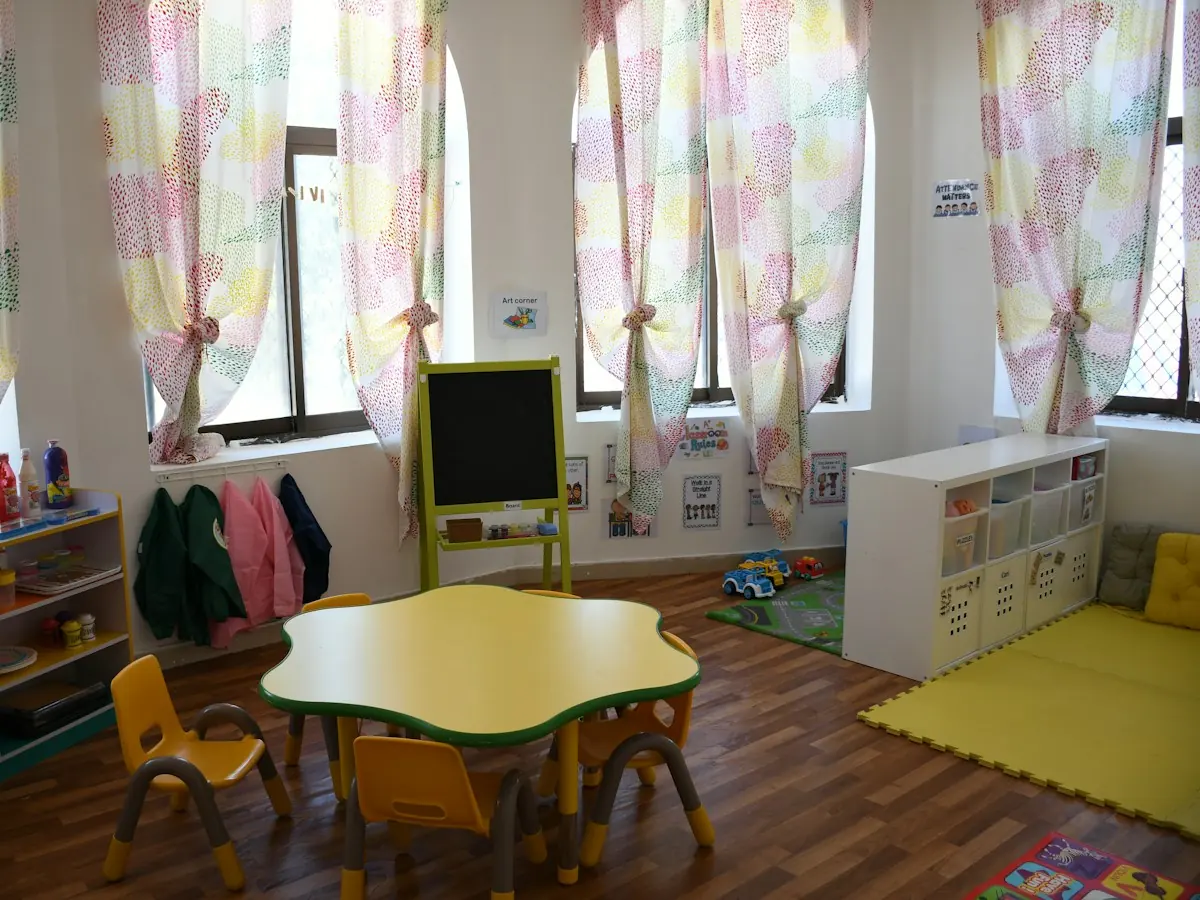
Can a daycare close a gap in coverage before it costs its early-learning contract?
A child care center in FloridaHer coverage now runs with no gap, and the program confirmed her case no longer needed to go to management.
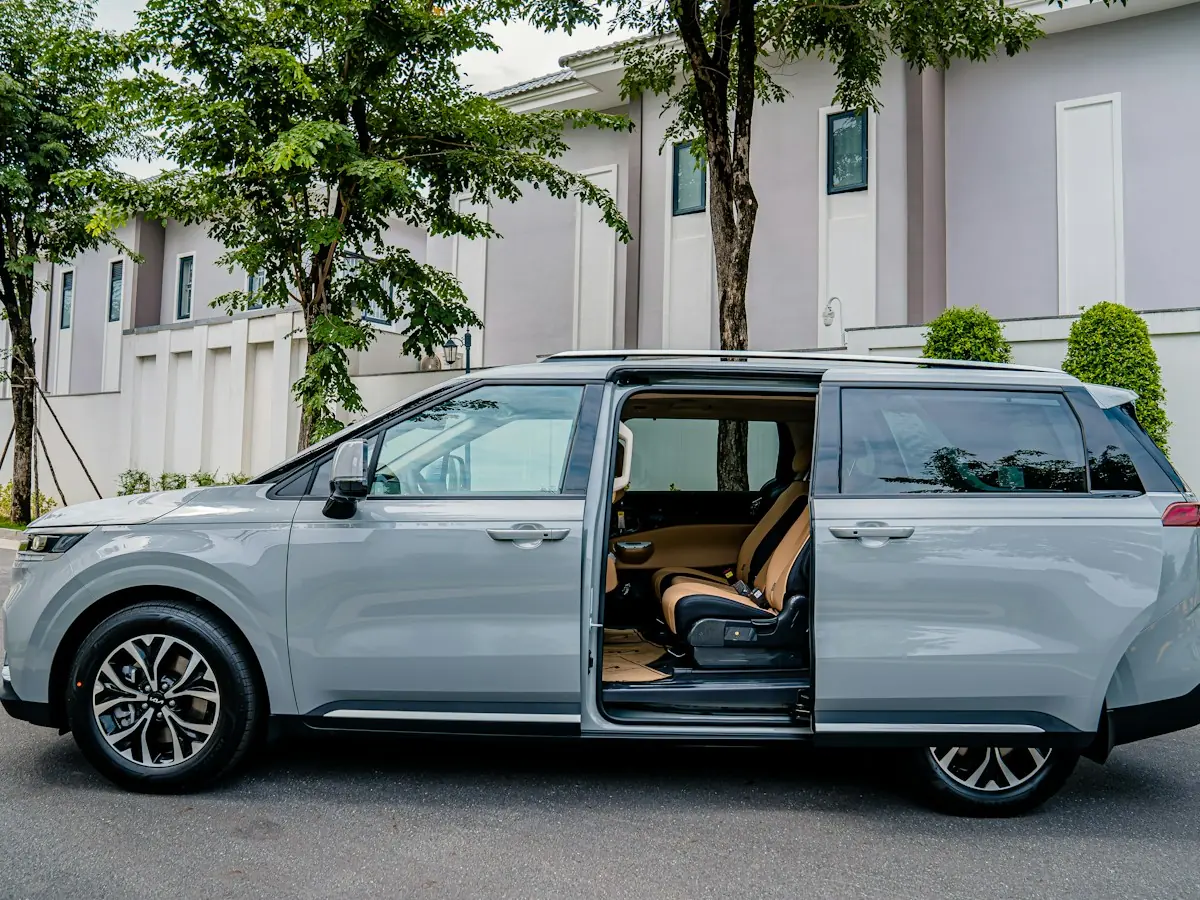
Can an in-home daycare insure the van it uses to drive children to school?
A family child care home in CaliforniaAll three policies were in place within about ten days of her first call, with certificates for the funder, and the grant paying for her first year went ahead.
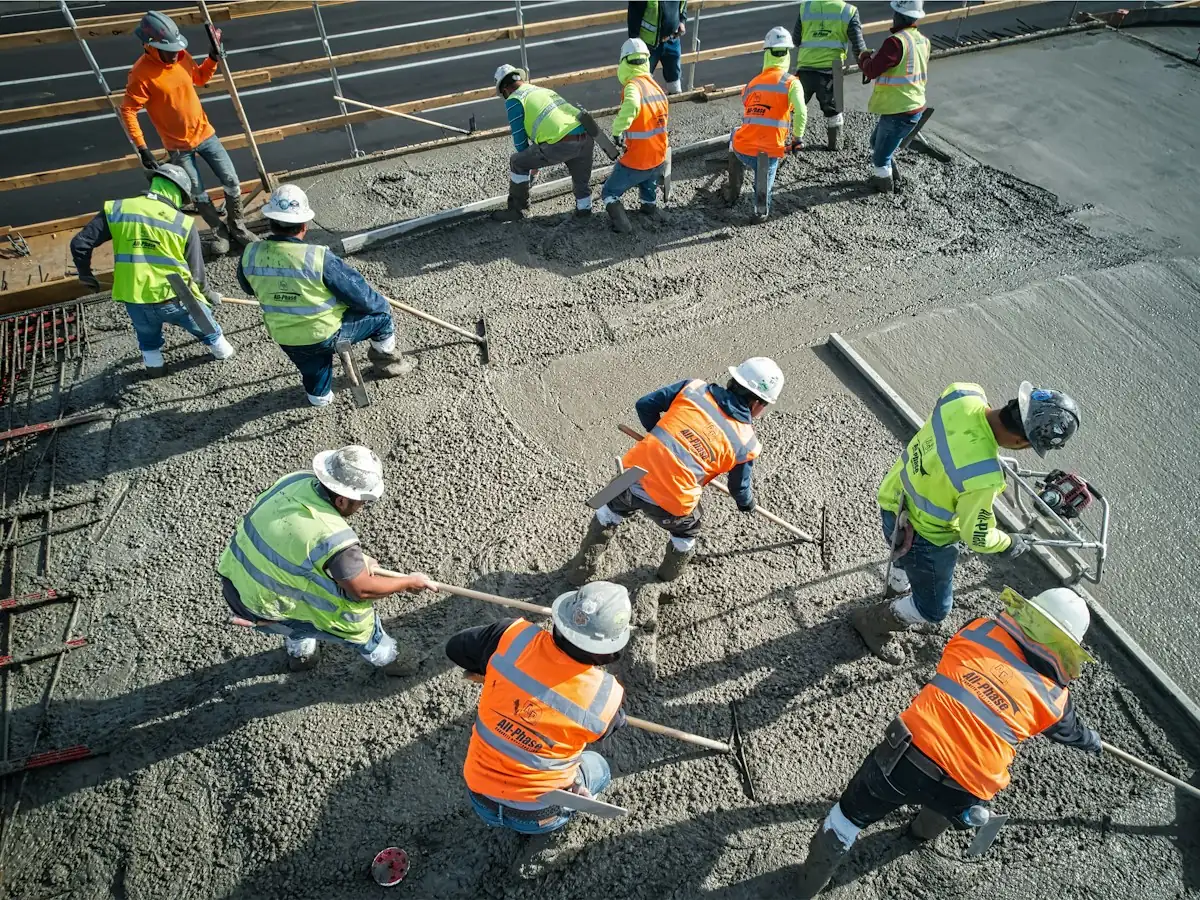
Can a concrete contractor meet a city’s insurance rules for a right-of-way permit?
A residential concrete contractor in VirginiaHe was bound about three hours after his first call, and the certificate and additional-insured endorsement went to the city that evening.
Can a crane company get insured after a long gap in coverage and a same-day decline?
A crane rental company in NevadaGeneral liability was bound within a week of the first call, followed by an equipment policy for the cranes and a fleet auto policy that covers them on the road.
Can a security patrol company get commercial auto when specialty insurers won’t write it?
An unarmed security patrol company in CaliforniaThe patrol cars were insured, and the policy has kept pace as the fleet changed.
Can new owners of two restaurants get liquor liability with no loss history in their name?
Two full-service sushi restaurants in Florida, under new ownershipGeneral liability with $1M of liquor liability was bound at both stores the same day the owners saw the comparison, and landlord certificates were ready that day.
Can a new child care center put its preschool funding program’s insurance list in place in days?
A child care center in ColoradoHer policies now carry a $2M aggregate, abuse and molestation coverage, workers’ comp, and the program, the city and the state agency as additional insureds. Certificates went to the local program and the state.
Can a child care center replace its insurance in a day when its insurer drops the policy?
A child care center in MissouriLiability and contents were covered from the first day. The new liability has a higher general aggregate than the old policy, and its abuse coverage has a higher total limit.
Can a brand-new guard company get its license certificate in days, and workers’ comp in an afternoon?
An unarmed security guard company in VirginiaThe license application had its certificate the day after binding. The company now carries general liability and workers’ comp, and certificates went to the firm it subcontracts for and to a facility client.
Will a state licensing board accept a non-admitted liability policy for a new guard company?
An unarmed security guard company in MinnesotaThe policy was bound to start on the date the owner chose. It carries $1M per occurrence and $2M aggregate, personal injury coverage including false arrest, and the board’s cancellation-notice endorsement. The certificate and policy copy were ready for his license filing.
Can a framing contractor get general liability after a gap in coverage, without prior loss runs?
A residential framing contractor in ArizonaGeneral liability at $1M per occurrence and $2M aggregate took effect five days after the first call, with blanket additional insured for ongoing work, primary and non-contributory wording, and a waiver of subrogation.
Can a restaurant meet a landlord’s higher liability limits before signing a lease amendment?
A family restaurant in ColoradoThe restaurant’s liability now meets or exceeds every limit in the lease clause: $2M per occurrence, $4M aggregate and $500K for the premises, with the landlord’s companies covered as additional insureds. It was in place about two days after his first call.