 (302) 213-6772
Can a security patrol company get commercial auto when specialty insurers won’t write it? Yes. Here’s how Soma did it.
The patrol cars were insured, and the policy has kept pace as the fleet changed.
What happened
The situation
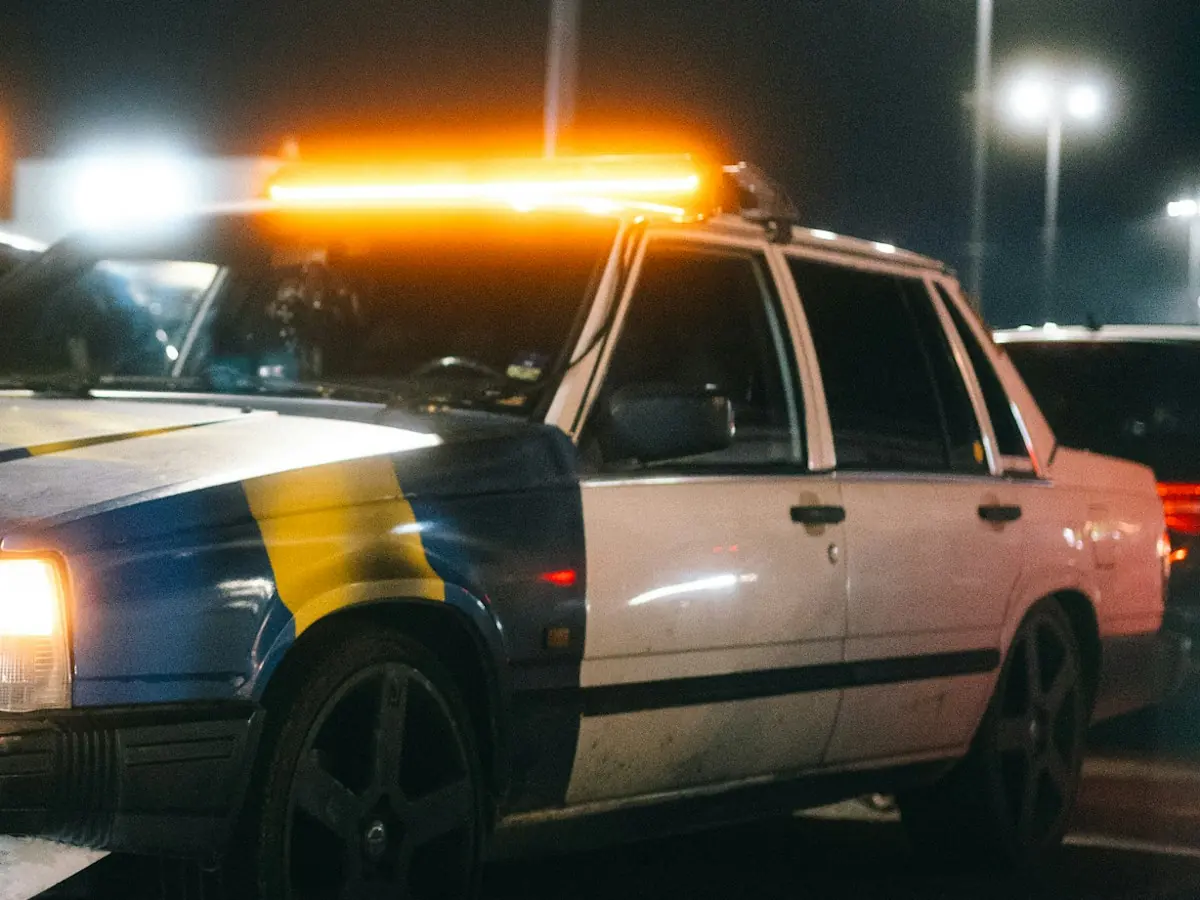
A company that runs unarmed patrols for apartment communities and childcare centers needed commercial auto for its patrol cars. It had been operating for only a few months and wanted a better price than its first auto policy.
What made it hard
Specialty markets passed on it.
How it got solved
We took it to a specialty underwriter that focuses on small transportation fleets and answered every question it raised: unarmed only, who the company patrols for, how far the cars travel, the drivers’ clean records, loss history, and why coverage had only recently started. Once firm terms came back we bound within days, then added vehicles and drivers mid-term as the company grew.
More problems solved
Can a brand-new guard company get its license certificate in days, and workers’ comp in an afternoon?
An unarmed security guard company in VirginiaThe license application had its certificate the day after binding. The company now carries general liability and workers’ comp, and certificates went to the firm it subcontracts for and to a facility client.
Will a state licensing board accept a non-admitted liability policy for a new guard company?
An unarmed security guard company in MinnesotaThe policy was bound to start on the date the owner chose. It carries $1M per occurrence and $2M aggregate, personal injury coverage including false arrest, and the board’s cancellation-notice endorsement. The certificate and policy copy were ready for his license filing.