 (302) 213-6772
Can a restaurant meet a landlord’s higher liability limits before signing a lease amendment? Yes. Here’s how Soma did it.
The restaurant’s liability now meets or exceeds every limit in the lease clause: $2M per occurrence, $4M aggregate and $500K for the premises, with the landlord’s companies covered as additional insureds. It was in place about two days after his first call.
What happened
The situation
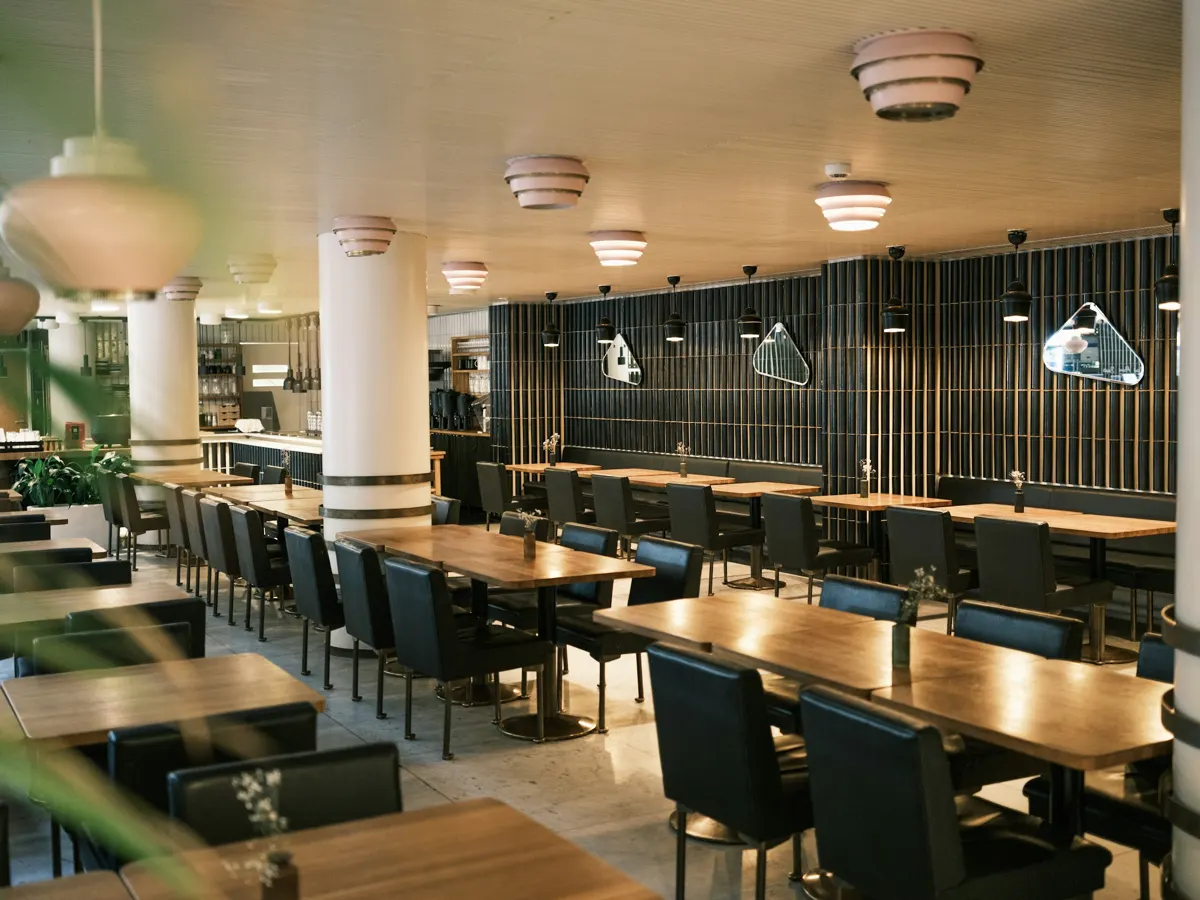
A new owner taking over an established family restaurant that serves no alcohol needed general liability before he could sign a lease amendment. We quoted and bound a policy on his first call.
What made it hard
The landlord’s review came in rounds. It wanted exact certificate-holder wording for its ownership and management companies, additional-insured status by endorsement, and limits above a standard policy: $2M per occurrence, $3M aggregate and $500K for fire damage to the premises. The insurer could raise limits only by writing a new policy, not by endorsement.
How it got solved
Within minutes of the first request we reissued the certificate with the landlord’s exact wording and sent the blanket lessor additional-insured, primary and non-contributory, and waiver of subrogation endorsements. When the limits request came, we confirmed the insurer’s options and wrote a replacement policy at the higher limits the next day. We then matched the certificate and the policy to the address in the lease.
More problems solved
Can new owners of two restaurants get liquor liability with no loss history in their name?
Two full-service sushi restaurants in Florida, under new ownershipGeneral liability with $1M of liquor liability was bound at both stores the same day the owners saw the comparison, and landlord certificates were ready that day.
Can an in-home daycare insure the van it uses to drive children to school?
A family child care home in CaliforniaAll three policies were in place within about ten days of her first call, with certificates for the funder, and the grant paying for her first year went ahead.