 (903) 289-5495
Can an in-home daycare insure the van it uses to drive children to school? Yes. Here’s how Soma did it.
All three policies were in place within about ten days of her first call, with certificates for the funder, and the grant paying for her first year went ahead.
What happened
The situation
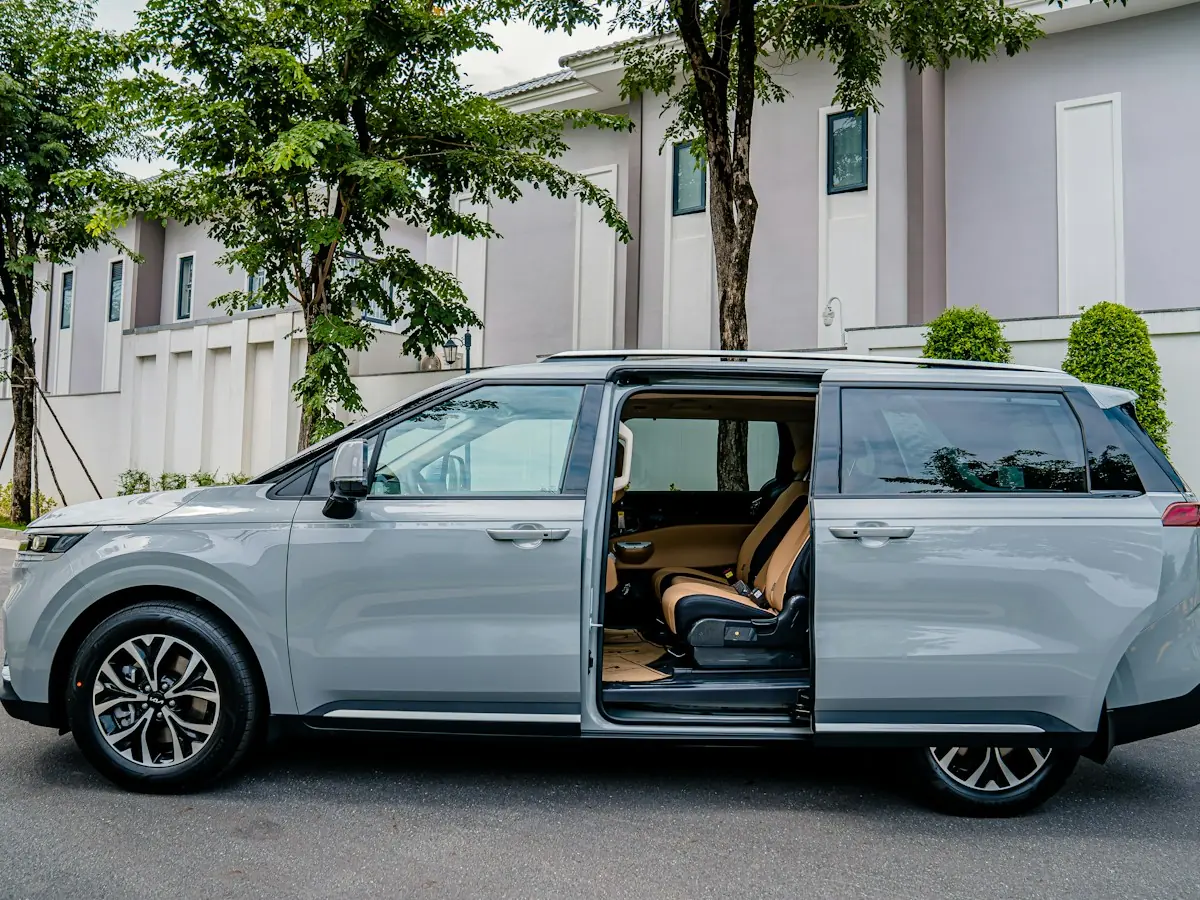
A licensed in-home daycare was moving up from a small to a large family child care license and had no business insurance in place. It drove children to and from nearby schools in a 15-passenger van that sat on a personal auto policy.
What made it hard
A van carrying children for a business needs commercial auto. A grant paying for her first year of insurance had its own checklist, and she needed quotes for a meeting with the funder the next day.
How it got solved
On the first call we quoted general liability that cleared the new license’s limit, with childcare professional liability included. The next morning we sent the van, driver and route details to a commercial auto market that writes passenger vans, and had a $1M quote back within hours. We laid out the general liability, auto and workers’ comp quotes against the funder’s checklist.
“Great help they really did everything for me to find the insurance that I needed”
More problems solved
Can a new child care center put its preschool funding program’s insurance list in place in days?
A child care center in ColoradoHer policies now carry a $2M aggregate, abuse and molestation coverage, workers’ comp, and the program, the city and the state agency as additional insureds. Certificates went to the local program and the state.
Can a daycare close a gap in coverage before it costs its early-learning contract?
A child care center in FloridaHer coverage now runs with no gap, and the program confirmed her case no longer needed to go to management.